Ohio Sales Tax Exemption for Manufacturing
AGILE CONSULTING GROUP
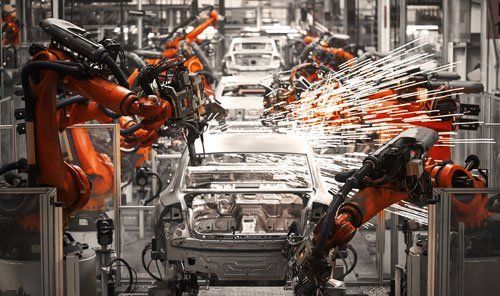
Examples of Purchases Which Qualify for the Ohio Sales Tax Exemption
- Production machinery and equipment that act upon the product
- Machinery and equipment used to treat parts or materials in preparation for the manufacturing operation
- Materials handling equipment that moves work in process, such as forklifts
- Equipment that temporarily stores the product during the manufacturing operations
- Consumables that interact with the product and are integral to the manufacturing operation such as catalysts, solvents, water, acids, or oil
- Machinery, equipment or other tangible personal property used to test raw materials, the product being manufactured, or the completed product
- Electricity, gas, water, steam or any other fuel or source of power for machinery used in the manufacturing operation
- Parts, components, and repair and installation services for any of the above referenced machinery and equipment
How to Claim the Ohio Sales Tax Exemption for Manufacturing
To claim the Ohio sales tax exemption for manufacturing, qualifying manufacturers need to complete Ohio sales tax exemption Form STEC B, which is a Sales and Use Tax Blanket Exemption Certificate, and provide a copy of this certificate to their vendors. In addition to requiring purchaser information, such as name, address, and business type, Ohio Form STEC B also requires an explanation for why the purchaser is claiming an exemption. This explanation should include the qualifying exempt items (i.e. repair parts used for production machinery) as well as the specific statute in Ohio sales tax law that provides the exemption.
Maximize Your Sales Tax Savings with Agile Consulting Group
Manufacturers Can Recover Sales Taxes They Have Already Paid
For manufacturers who have already paid sales taxes to their vendors or self-assessed use taxes on their Ohio UUT 1 use tax return, they can complete and submit Ohio Form ST AR, which is a Sales/Use Tax Application for Refund, to recover sales taxes on qualifying tangible personal property used directly in a manufacturing operation. The ST AR must be filed within four years from the payment date of the tax, otherwise, the statute of limitations will have lapsed, and any taxes paid in error will not be eligible for a refund. The STEC B and ST AR forms are both located on the Ohio Department of Revenue website. The experienced consultants at the Agile Consulting Group can provide guidance and assistance with the completion of both forms.
As with all sales and use tax research, the specifics of each case need to be considered when determining taxability. Additional advice from Agile Consulting Group’s sales tax consulting team can be found on our page summarizing Ohio sales and use tax exemptions.
Reach Out to Us with Questions
If you have questions, comments or would like to discuss the specific circumstances you are encountering in regard to this issue or any other sales and use tax issue, please contact a member of Agile Consulting Group’s
sales tax consulting team at (888) 350-4TAX (4829) or via email at
info@salesandusetax.com.
Latest Insights