Connecticut Manufacturing Sales Tax Exemption for Machinery

AGILE CONSULTING GROUP

November 12, 2016

Share this article

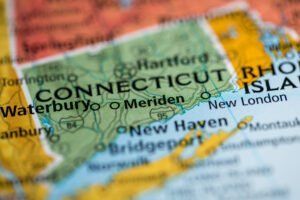
Map of Connecticut with nearby cities highlighted, including Hartford, New Haven, and Waterbury.

In accordance with Connecticut Agencies Regulations 12-412(34)-1 and Connecticut General Statutes 12-412(34), Connecticut offers a broad exemption for machinery used directly in a manufacturing production process.

For the purposes of this exemption, a business must substantially alter raw or finished materials into a product possessing new characteristics in order to be considered a manufacturer. Additionally, the production process must result in a good or product that is intended for resale. The following are guidelines in determining whether a process qualifies as manufacturing under the Connecticut manufacturing machinery exemption. 

Connecticut Manufacturing Machinery Exemption

Key Considerations

A key concept in the application of the Connecticut manufacturing machinery exemption is “direct use.”  Machinery and equipment that qualify for the Connecticut manufacturing machinery exemption must be used directly in the manufacturing production process.  “Direct use” is determined by the following principles: 

Businesses that qualify for this exemption can request a refund from the state of Connecticut for sales tax paid in error. Labor is generally taxable, only purchases of tangible personal property will qualify for this exemption. Additional industry specific exemptions are also available.

Why Choose Agile Consulting?

As with all Sales & Use Tax research, the specifics of each case need to be considered when determining taxability.  Agile Consulting Group’s sales tax consultants can be found on our page summarizing Connecticut sales and use tax exemptions .  If you have questions, comments or would like to discuss the specific circumstances you are encountering in regard to this issue or any other Sales & Use Tax issue, please contact us at (888) 350-4TAX or (888) 350-4829 or via email at info@salesandusetax.com .  

Citations: 

Connect With Us

Latest Insights

Lighthouse and white house on rocky coast at sunset with pink clouds over the sea
By Aaron Giles • October 13, 2026
Learn which wound closure products qualify for Maine’s sales tax exemption and how healthcare facilities can claim exemptions or recover overpaid taxes.
Nurse bandaging a patient’s hand in a clinic, wearing blue gloves and scrubs
By Aaron Giles • October 7, 2026
Wyoming healthcare providers may qualify for a sales tax exemption on wound care products. Learn eligibility requirements, qualifying supplies, and refund options.